Publications
Books and research by Dr Anna Serbinenko
Books
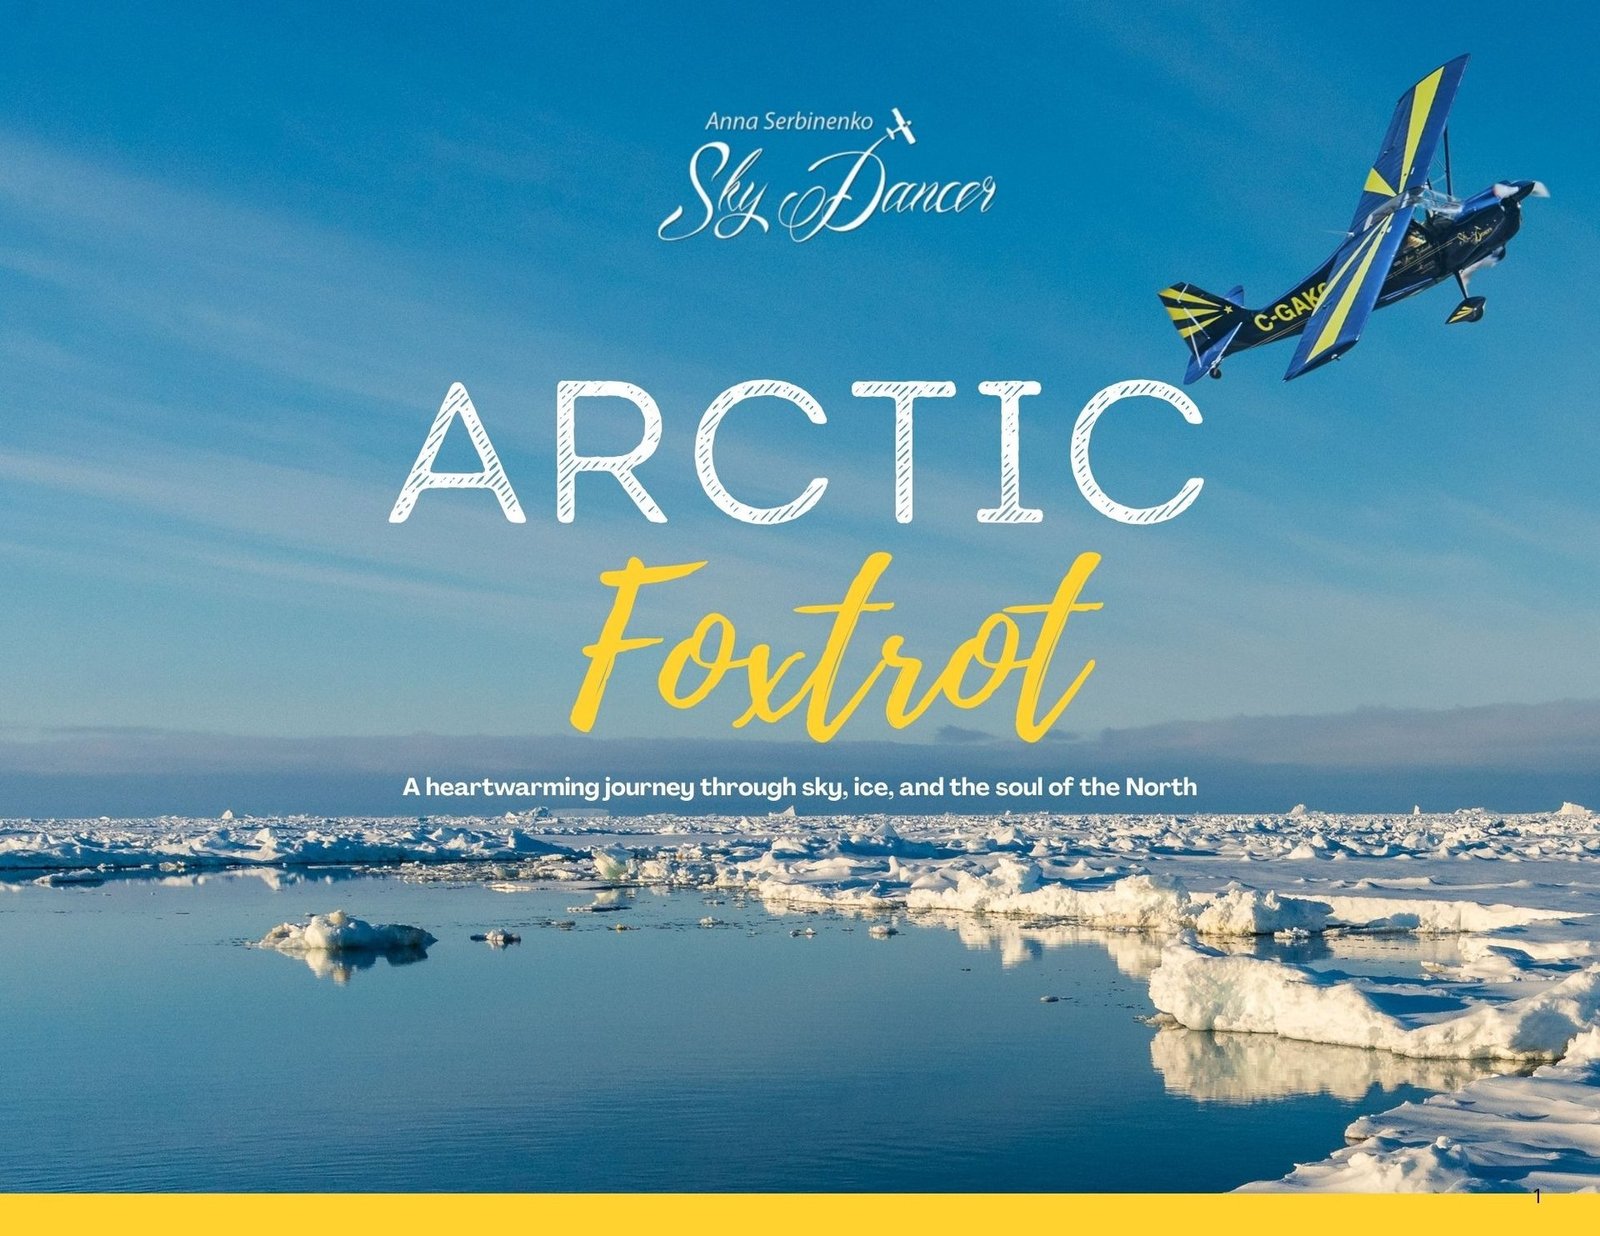
Arctic Foxtrot
A heartwarming journey through sky, ice, and the soul of the North.
A photo book of my flight from Boundary Bay to Tuktoyaktuk on the Arctic Ocean, told as a daily log: Fort Liard, Whitehorse, Dawson City, Old Crow, Inuvik and beyond.
Flight training guides
Practical guides for pilots, from the first licence to the instructor rating.

Pilot License for Future Pilots

Flight Instructor Rating

IFR Rating

Multi-Engine Rating

Taildragging for Pilots

Aerobatics for Pilots
Paper copies are at the Flight Store, Pitt Meadows Regional Airport: flightstorecypk@gmail.com
Science research
My PhD and earlier work in financial mathematics and statistics, at the universities of Neuchâtel and Fribourg in Switzerland and Karlsruhe in Germany.
Papers and theses
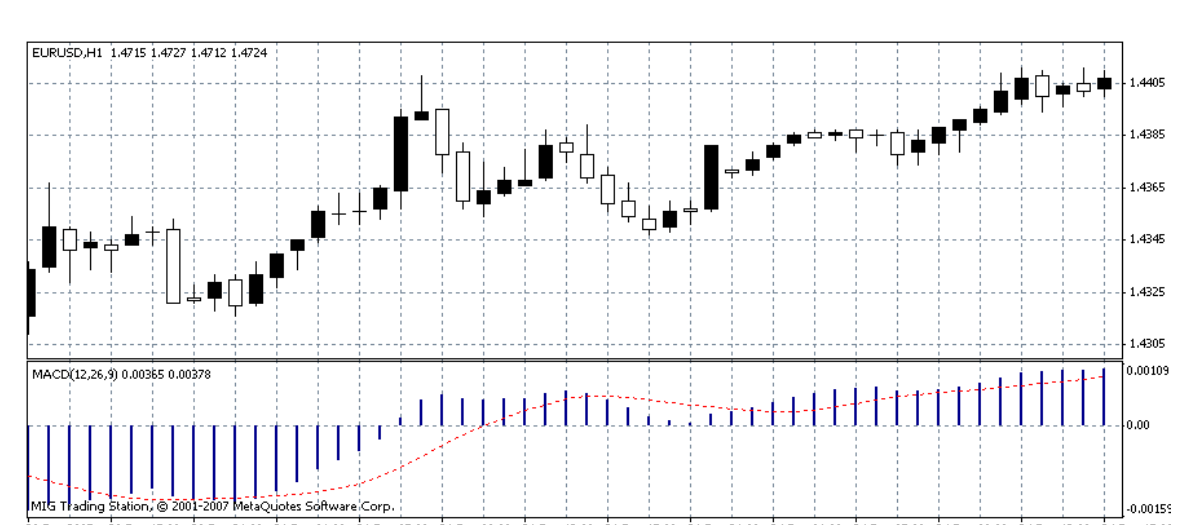
- Econometric Model for Intraday Trading on the Spot Foreign Exchange Market, PhD thesis, University of Karlsruhe, 2009
- A New Hybrid Model for Intraday Spot Foreign Exchange Trading, Accounting for Heavy Tails and Volatility Clustering, with S. T. Rachev, Journal of Computational Analysis and Applications, 2009
- Intraday Spot Foreign Exchange Market: Analysis of Efficiency, Liquidity and Volatility, with S. T. Rachev, Investment Management and Financial Innovations, 2009
- ARIMA, Cointegration, Kalman Filter, α-stable Distributions, Proceedings in Applied Mathematics and Mechanics (PAMM), 2008
- Returns of Eastern European Financial Markets: α-stable Distributions, Measures of Risk, with J. F. Emmenegger, PAMM (ICIAM 2007, Zurich), Wiley
- Returns of Eastern European Financial Markets: ARMA, GARCH Modelling, α-stable Distributions, International Journal of Pure and Applied Mathematics, 2007
- Discrete Fourier Transform to Calculate α-stable Distributions: Application to Risk Evaluation, with J. F. Emmenegger, Symposium on Agent-Based Modelling, Risk and Finance, Fribourg, 2007
- The Stable Paretian Hypothesis of Mandelbrot and the Gaussian Hypothesis of Bachelier: Two Concepts Applied in Mathematical Finance, talk at the 4th International Conference of Applied Mathematics and Computing, Plovdiv, 2007
- Index Returns of Eastern European Financial Markets: ARMA-GARCH Modelling and Detection of Structural Breaks, Master’s thesis, 2006
- Evolution of University Studies in Switzerland, with Y. Dodge and K. Iglesias, Institute of Statistics, University of Neuchâtel
- The Close Formula for Orthogonal L2 Regression, STUDENT, vol. 4, no. 4, 2003
Contributions to books
- Statistique : dictionnaire encyclopédique, Y. Dodge, Springer, 2004: edited in French and translated into English
- Optimisation appliquée, Y. Dodge, Springer, 2002: corrections
- The Oxford Dictionary of Statistical Terms, Y. Dodge, Oxford University Press, 2002: corrections
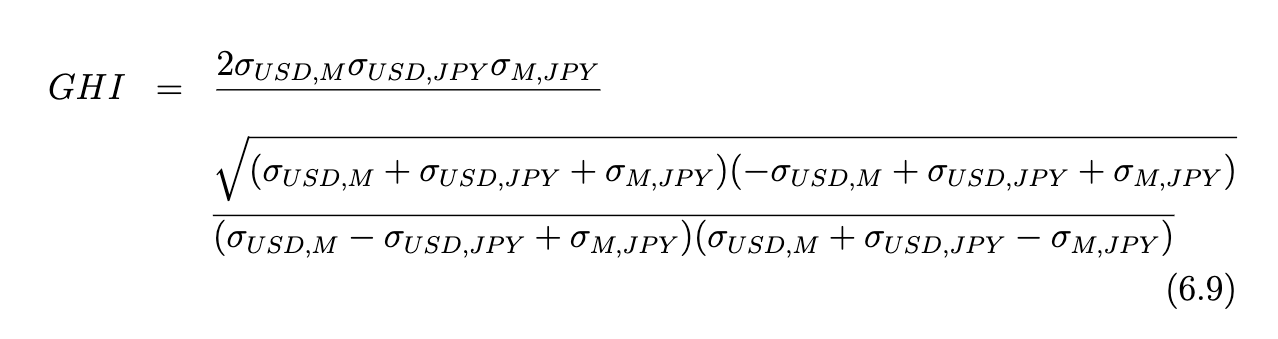
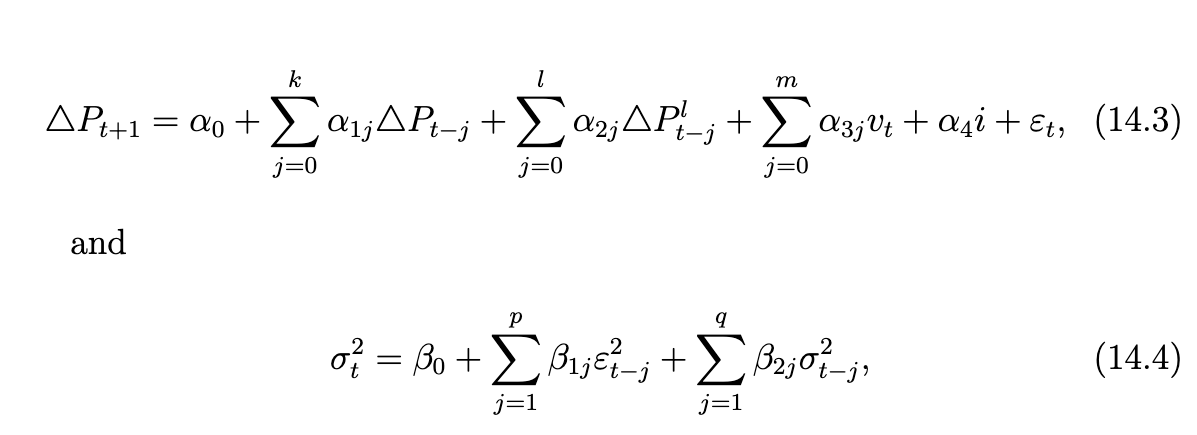
Passion projects
Bible illustrations
Christian aviation jazz
Wings album